
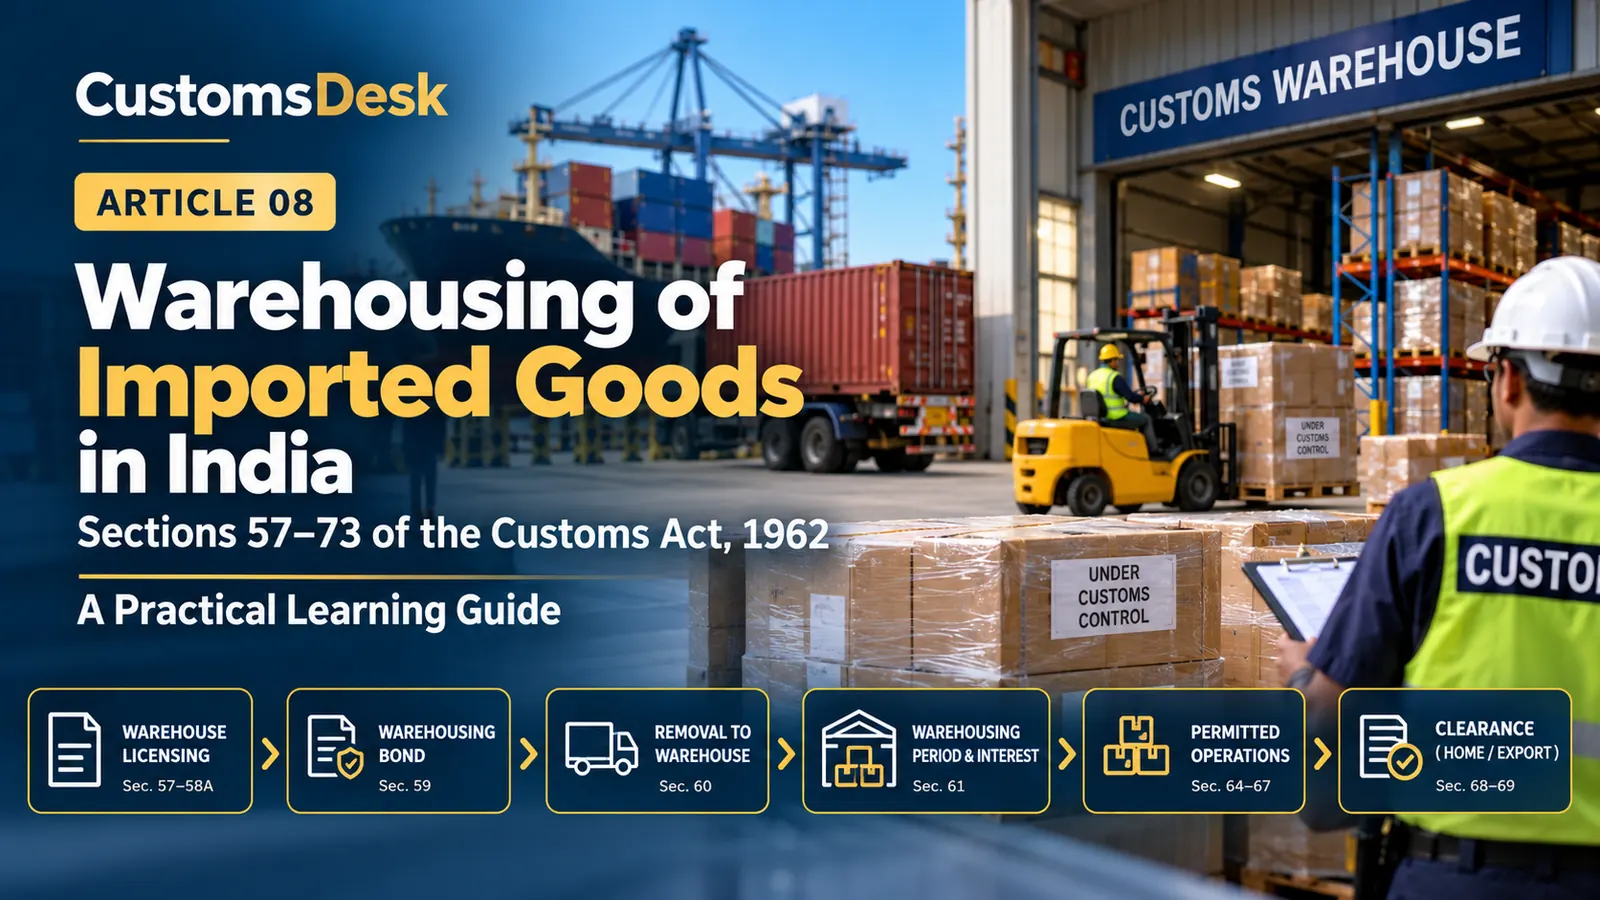
Warehousing of Imported Goods in India
Sections 57–73 of the Customs Act, 1962: A Practical Learning Guide
In Article 07, we followed imported goods through assessment, examination, duty payment and clearance for home consumption under Section 47. But what if an importer does not want to clear the goods for home consumption immediately?
Indian Customs law provides a separate framework for warehousing eligible imported goods. This chapter explains how that framework operates, what responsibilities continue while goods remain in a warehouse, and how the goods may subsequently be cleared or exported.
By the end of this article, you should understand the difference between home-consumption clearance and warehousing, the purpose of a warehousing bond, the significance of Section 61, permitted operations under Section 65, and the routes for clearance under Sections 68 and 69.
1. From Article 07 to Article 08
Examination
Section 47 Clearance
Warehousing Route
Article 07 dealt with goods being cleared for home consumption. Article 08 explores the alternative legal route in which goods are entered for warehousing, deposited in an authorised warehouse after the required procedures, and later dealt with under the warehousing provisions.
Warehousing is not simply putting imported goods in an ordinary storage facility. It is a statutory Customs arrangement with prescribed procedures, authorised premises, records and continuing obligations.
2. What Does Customs Warehousing Mean?
Customs warehousing allows eligible imported goods to be deposited in a warehouse under the Customs Act, subject to the relevant legal requirements. The arrangement can defer payment of import duty until the goods are cleared, but it does not mean that duty is automatically cancelled or that the goods are free from Customs control.
3. Public, Private and Special Warehouses
The Act provides for different warehouse categories. Their legal basis and conditions are not identical.
| Provision | Subject | Practical understanding |
|---|---|---|
| Section 57 | Licensing of public warehouses | Provides the statutory basis for licensing a public warehouse in which dutiable goods may be deposited. |
| Section 58 | Licensing of private warehouses | Provides for a private warehouse for dutiable goods imported by or on behalf of the licensee, subject to applicable conditions. |
| Section 58A | Licensing of special warehouses | Provides a special warehouse framework, including statutory controls over entry and removal and the classes of goods that may be specified. |
| Section 58B | Cancellation of licence | Addresses cancellation in circumstances specified by law, including relevant contraventions or breaches of licence conditions. |
The applicable licensing regulations and warehouse custody and handling requirements must also be checked. Do not assume that every warehouse has the same permissions or operational conditions.
4. Why Is Section 59 Important?
Section 59 deals with the warehousing bond. In general terms, the importer of goods entered for warehousing and assessed under the relevant statutory framework must execute the prescribed bond and furnish security as required by law.
The bond supports the importer’s obligations relating to compliance with the Act and the rules and regulations, and payment of applicable duty, interest, penalties and fines where they become payable.
A warehousing bond is not merely an administrative formality. It is part of the legal framework that secures the obligations associated with goods deposited in a Customs warehouse. Verify the current statutory wording, prescribed forms, security requirements and any applicable facility before executing it.
5. Section 60: Permission to Remove Goods to the Warehouse
After the applicable Section 59 requirements have been complied with, Section 60 provides for an order by the proper officer permitting removal of the goods from the Customs station for deposit in a warehouse. The provision also recognises electronic orders through the Customs automated system under the prescribed risk-evaluation framework.
This is a simplified learning flow. Actual filing, movement, custody and deposit requirements must be checked against current Customs procedures and the relevant warehouse regulations.
6. Section 61: How Long Can Goods Remain Warehoused?
Section 61 governs the period for which goods may remain warehoused. The applicable period depends on the category of goods and the statutory provisions in force. It is therefore unsafe to assume that all goods have one universal warehousing period.
The section also contains specific interest provisions for the categories and circumstances covered by it. The relevant dates, statutory category, applicable rate and any notification or waiver must be checked before calculating interest.
Do not use an outdated warehousing-period summary or calculate interest from memory. Verify the current text of Section 61, the date on which the relevant order was made, the category of goods and applicable notifications for the actual transaction.
Practical controls for an importer
- Maintain an accurate inventory of warehoused goods and their identifiers.
- Track the date of the warehousing order and the applicable statutory period.
- Monitor duty, interest and bond obligations.
- Keep warehouse records and supporting documents available.
- Obtain the required permission before transferring, removing or carrying out operations on warehoused goods.
7. Sections 64–67: Dealing With Goods in a Warehouse
| Section | Topic | Why it matters |
|---|---|---|
| Section 64 | Owner’s right to deal with warehoused goods | Recognises dealings with goods subject to the conditions and permissions prescribed by the Act. |
| Section 65 | Manufacture and other operations in a warehouse | Provides a framework for permitted manufacturing or other operations, subject to the applicable authorisation and conditions. |
| Section 66 | Power to exempt imported materials used in manufacture in a warehouse | Provides a statutory power concerning exemption, subject to its terms and applicable conditions. |
| Section 67 | Removal of goods from one warehouse to another | Provides the legal framework for authorised transfer between warehouses. |
Do not assume unrestricted use. Storage, repacking, processing, manufacturing, transfer or other dealings must be assessed against the exact statutory provision, permissions, regulations and conditions applicable to the goods and warehouse.
8. Section 68 vs Section 69
This is one of the most important distinctions in the warehousing chapter.
| Point | Section 68 | Section 69 |
|---|---|---|
| Purpose | Clearance of warehoused goods for home consumption | Clearance of warehoused goods for export |
| Entry | Bill of Entry for home consumption in the prescribed form | Applicable export entry and prescribed procedure |
| Payment / conditions | Applicable import duty, interest, fine and penalties payable must be dealt with as required by the section. | Must satisfy the statutory requirements and conditions applicable to export clearance. |
| Order | Clearance order by the proper officer is required. | Export clearance must be authorised under the applicable legal framework. |
Section 47 concerns clearance for home consumption through the general import-clearance route. Section 68 deals with clearance for home consumption of goods that have already been warehoused. The routes are related, but they are not interchangeable.
9. ABC India Pvt. Ltd.: The Warehousing Decision
In Article 06, ABC India imported an industrial machine and Customs examined the declaration and technical documents. In Article 07, we followed the Section 47 route for home-consumption clearance.
Now consider a different commercial decision: ABC India does not need the machine immediately and wants to explore whether the statutory warehousing route is appropriate.
Step 1 · Choose the correct entry
ABC India must assess whether a Bill of Entry for warehousing is suitable and complete the prescribed entry and assessment procedures. A home-consumption Bill of Entry should not simply be treated as a warehousing entry.
Step 2 · Complete the bond and removal process
ABC India must comply with the relevant bond and security requirements and obtain the required permission for removal to the authorised warehouse under Section 60.
Step 3 · Maintain compliance while goods are warehoused
The importer must monitor the goods, records, applicable warehousing period, bond conditions and any interest or other obligations. It must not assume that goods can be freely moved, processed or removed without the necessary permissions.
Step 4 · Decide the final route
If ABC India later wants to use the machine in India, it must consider clearance for home consumption under Section 68, including the applicable Bill of Entry, payment and clearance-order requirements. If it intends to export the warehoused goods, it must consider Section 69 and its applicable conditions.
10. Sundaresh Bhatt v. Central Board of Indirect Taxes and Customs (2022)
The Supreme Court considered the interaction between Customs law and insolvency proceedings in a case involving goods and the authority of Customs in the relevant circumstances. The judgment is useful for understanding that the handling and release of goods subject to Customs control cannot be decided by ignoring the statutory framework.
How to use this case in the classroom: Treat it as a broader illustration of the interaction between Customs powers and another statutory regime. Do not present it as a direct ruling on every warehousing-period, bond or interest question under Sections 57–73.
Before relying on the case in a live matter, obtain and read the original judgment from the Supreme Court of India website and identify the exact issue and holding relevant to the facts.
For an article focused specifically on warehousing bonds, interest or expiry of the warehousing period, add a case only after confirming its original text, statutory context, holding and subsequent treatment. A related Customs judgment should not be labelled a direct Section 61 or Section 68 precedent without that verification.
11. Six Warehousing Mistakes to Avoid
- Confusing warehousing with duty exemption. Deferral is not the same as cancellation of duty.
- Using the wrong Bill of Entry route. Home-consumption and warehousing entries serve different purposes.
- Ignoring the bond. Bond and security obligations form part of the statutory framework.
- Assuming an unlimited storage period. Check Section 61 and any applicable notification or extension.
- Removing or processing goods without permission. Verify the applicable provisions and warehouse conditions first.
- Mixing up Sections 68 and 69. One concerns home consumption; the other concerns export clearance of warehoused goods.
12. Before Warehousing Imported Goods
- Confirm that the proposed goods and transaction qualify for the intended warehousing route.
- File the correct Bill of Entry and complete the applicable assessment requirements.
- Verify the warehouse licence and the conditions applicable to the goods.
- Complete the Section 59 bond and security requirements as prescribed.
- Obtain the necessary Section 60 removal permission.
- Maintain inventory, custody and other required records.
- Track the applicable warehousing period and any interest exposure under the current law.
- Obtain permission before a transfer, removal or operation that requires it.
- When ready, follow Section 68 for home consumption or Section 69 for export, as applicable.
- Retain the relevant entry, bond, payment, permission and clearance records.
This is a general learning checklist. The exact requirements depend on the goods, warehouse, statutory category and applicable procedures.
13. Test Your Understanding
Q1. Does warehousing automatically exempt imported goods from Customs duty?
Answer: No. It can defer duty payment subject to the statutory framework; duty and other obligations may become payable when the goods are cleared.
Q2. Which section deals with the warehousing bond?
Answer: Section 59.
Q3. Which provision addresses permission to remove goods for deposit in a warehouse?
Answer: Section 60.
Q4. Can all goods remain warehoused for the same period?
Answer: No. The applicable period must be determined under Section 61 and the provisions applicable to the particular category.
Q5. Which section concerns clearance of warehoused goods for home consumption?
Answer: Section 68.
Q6. Which section concerns clearance of warehoused goods for export?
Answer: Section 69.
Q7. Can an importer freely remove goods from a warehouse without following Customs requirements?
Answer: No. The goods must be dealt with in accordance with the Act, applicable permissions and warehouse requirements.
14. Official Sources
- India Code · Customs Act, 1962 (PDF) · See Chapter IX, Warehousing, and the current statutory text.
- CBIC Tax Information Portal · Section 68: Clearance of warehoused goods for home consumption
- CBIC Tax Information Portal · Section 46: Entry of goods on importation
- ICEGATE · Indian Customs electronic services
- Supreme Court of India · Judgments and orders
Always verify the current Act, applicable rules, notifications, warehouse regulations and original judicial decisions before applying this material to a live transaction.
15. The Big Picture
Customs warehousing is a regulated route for eligible imported goods to be deposited in an authorised warehouse under prescribed conditions. The framework includes warehouse licensing, bond and security, permission for removal, warehousing periods, permitted dealings and subsequent clearance.
Section 68 governs clearance of warehoused goods for home consumption, while Section 69 concerns clearance for export. The importer must track applicable duty, interest, time limits, records and permissions throughout the process.
Disclaimer: This article is for general educational and professional awareness only. It is not legal, tax or customs-clearance advice. The applicable treatment depends on the goods, transaction, relevant date, statutory provisions and current notifications. Verify official sources before acting.


Leave a Reply