
CustomsDesk · Live Updates
Daily Customs & DGFT Update
Customs, foreign trade policy, export promotion, trade remedies and export compliance.
01 | Executive Summary
| Authority / Development | Key Update | Who Should Review It? |
|---|---|---|
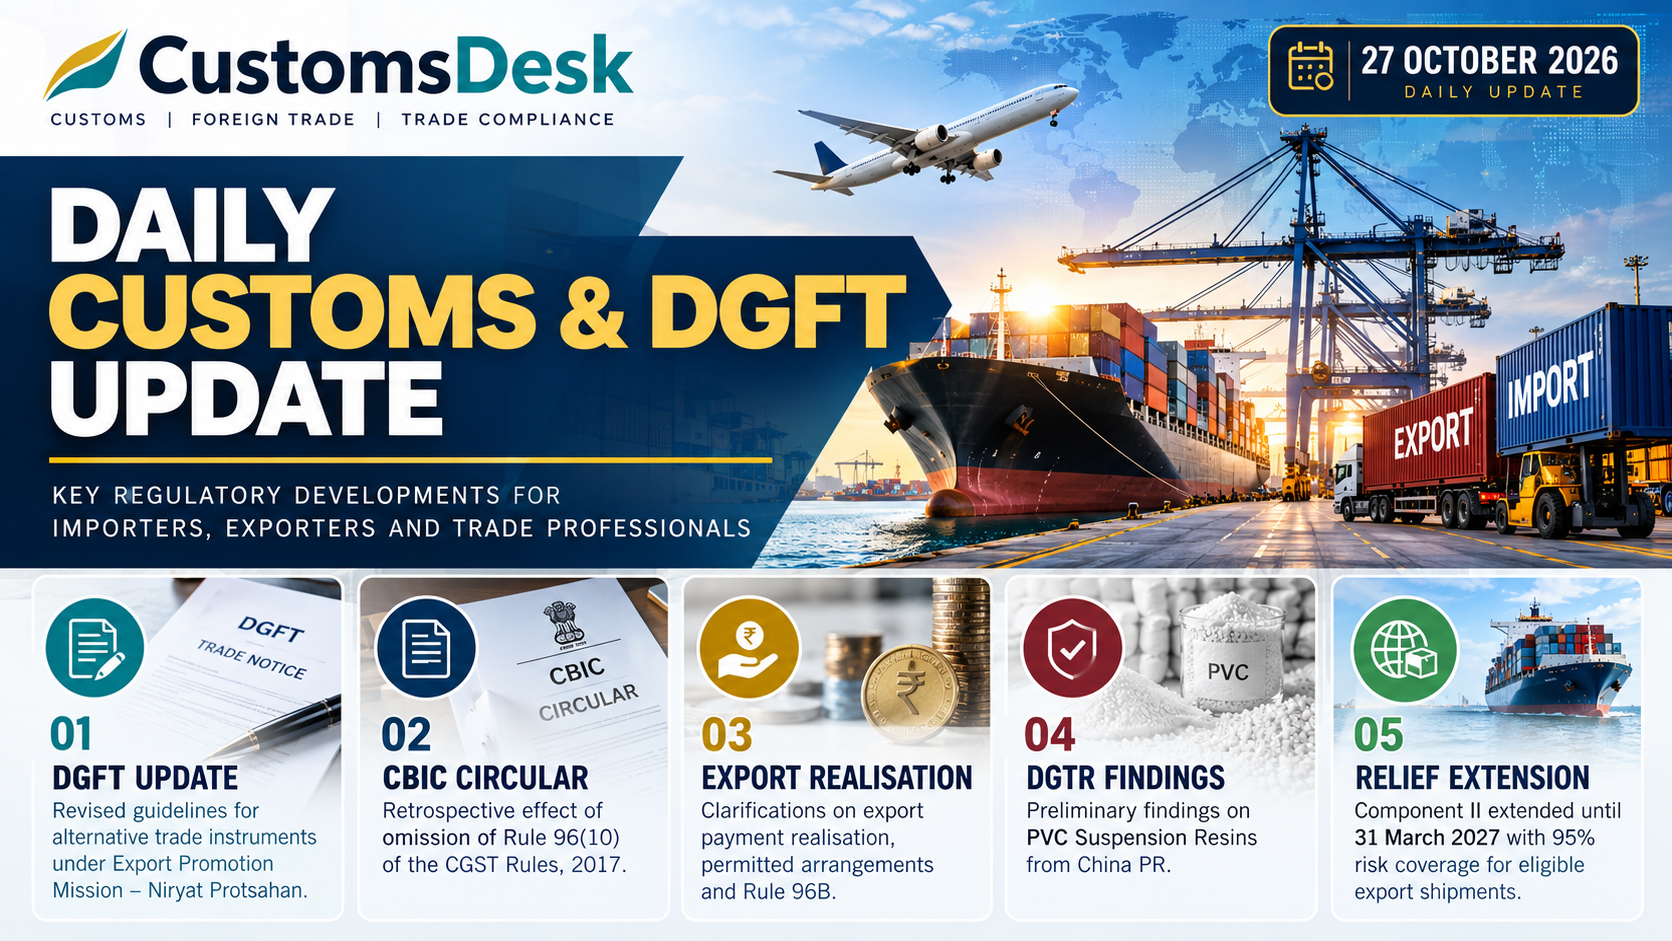
| DGFT Trade Notice No. 32/2026-27 | Amendments and clarifications to support for alternative trade instruments under EPM – Niryat Protsahan. | Eligible MSME exporters, export finance teams and trade-finance providers. |
| CBIC Circular No. 264/10/2026-GST | Clarification on the retrospective effect of the omission of Rule 96(10) of the CGST Rules, 2017. | Exporters with relevant refund claims or pending proceedings. |
| CBIC Circular No. 263/09/2026-GST | Clarifications concerning receipt of export payments, permitted payment arrangements and Rule 96B. | Exporters, finance teams and authorised dealer bank coordination teams. |
| DGTR: PVC Suspension Resins | Preliminary findings dated 26 October 2026 in the countervailing duty investigation concerning China PR. | Importers, producers, exporters and other interested parties dealing with the subject product. |
| RELIEF initiative | Component II timelines extended until 31 March 2027, with 95% risk coverage under the stated scheme framework. | Exporters shipping to eligible specified regions and reviewing ECGC cover. |
This digest summarises selected official developments relevant to customs, foreign trade and export compliance. Readers should consult the underlying circulars, notices, investigation documents and scheme conditions before taking action.
02 | DGFT: Export Promotion Mission – Niryat Protsahan
Trade Notice No. 32/2026-27 dated 26 October 2026
The Directorate General of Foreign Trade issued Trade Notice No. 32/2026-27 concerning amendments and clarifications to the guidelines for support for alternative trade instruments under the Export Promotion Mission (EPM), Niryat Protsahan.
The notice refers to the earlier framework introduced through Trade Notice No. 25/2025-26 dated 20 February 2026.
Key points highlighted
- UIN requirement: The notice addresses discontinuation of the requirement to submit a declaration of intent and obtain a Unique Identification Number (UIN) before availing the relevant factoring support.
- Concurrent support: The notice clarifies the interaction between interest subvention for pre-shipment and post-shipment export credit and support under the alternative trade instruments intervention, subject to the specified conditions.
- Existing framework: Other operational and procedural requirements continue unless amended by the notice or subsequent official instructions.
Eligible MSME exporters and their finance teams should review the revised application procedure, eligibility conditions and documentation requirements before applying. Removal of a prior UIN requirement should not be interpreted as removal of all other conditions or approvals.
Action point: Read Trade Notice No. 32/2026-27 together with the earlier guidelines and applicable annexures. Confirm the current procedure on the official DGFT portal.
Official source: Directorate General of Foreign Trade (DGFT)
Additional reference: Trade notice reference listing. Verify the operative text against the official DGFT publication.
03 | CBIC: Retrospective Omission of Rule 96(10)
Circular No. 264/10/2026-GST dated 26 October 2026
CBIC issued a clarification concerning the omission of Rule 96(10) of the Central Goods and Services Tax Rules, 2017, and the effect of that omission on matters relating to the earlier period.
The clarification addresses questions raised by taxpayers and tax officers concerning the retrospective applicability of the omission, in light of judicial decisions on the issue. The circular states that the omission is to be given effect from 23 October 2017.
Why exporters should review this circular
- Exporters whose refund claims or proceedings involve the former Rule 96(10) should examine the circular and the status of their specific matter.
- Businesses that imported inputs under applicable exemption or authorisation arrangements and subsequently faced refund-related disputes should assess whether the clarification is relevant to their records.
- Tax and finance teams should distinguish between the retrospective effect of the omission and the separate requirements for establishing entitlement to a refund.
Review pending show-cause notices, adjudication matters, refund claims and appeal records involving the former Rule 96(10). Determine whether any consequential submission or representation is appropriate in light of the circular and the procedural status of the matter.
Official portal: CBIC
Circular text: Circular No. 264/10/2026-GST. Use the official CBIC publication as the controlling source.
04 | CBIC: Export Payment Realisation and Rule 96B
Circular No. 263/09/2026-GST dated 26 October 2026
CBIC issued a clarification on receipt of payment for export of goods or services, addressing issues raised in relation to GST refunds and the application of relevant provisions.
Key areas addressed
- Receipt of export proceeds: The circular addresses specified payment arrangements and the recognition of receipts in accordance with the applicable conditions.
- Rupee accounts: It addresses permitted arrangements involving specified repatriable Indian rupee accounts, subject to the applicable requirements.
- Set-off arrangements: The clarification addresses situations where export receivables are set off against import payables, subject to compliance with applicable RBI directions.
- Rule 96B: The circular addresses the realisation of export proceeds and the circumstances in which recovery of a refund is not to be made where the requirement to realise the proceeds has been written off, wholly or partly, by an authorised dealer bank in accordance with the applicable framework.
- Specific business arrangements: The circular also addresses certain other payment-recognition situations. Exporters should consult the full text for the precise scope and conditions.
Exporters should review outstanding export receivables, applicable realisation deadlines, bank correspondence and supporting records. Where an authorised dealer bank has approved a relevant write-off, preserve the documentary evidence and assess the effect of the circular on the specific refund matter.
Action points for exporters
- Identify outstanding export receivables and check the applicable realisation period.
- Review authorised dealer bank documentation for any relevant write-off or permitted set-off.
- Assess pending refund or recovery matters against the circular’s precise wording.
- Retain supporting records and obtain professional advice where a demand, recovery or disputed claim is pending.
Official portal: CBIC
Circular text: Circular No. 263/09/2026-GST. Verify the operative text against the official CBIC publication.
05 | DGTR: PVC Suspension Resins from China PR
Preliminary findings dated 26 October 2026
The Directorate General of Trade Remedies (DGTR) published preliminary findings in the countervailing duty investigation concerning imports of PVC Suspension Resins originating in or exported from China PR.
The official investigation record should be consulted for the precise product description, scope, findings and procedural requirements.
Why this development matters
- Importers and buyers should review whether their products fall within the description and scope specified in the investigation documents.
- Producers, exporters and other interested parties should examine the preliminary findings and relevant procedural directions.
- Importers should assess potential sourcing and commercial exposure while monitoring subsequent official developments.
Review product specifications, tariff classification, country of origin and the investigation scope. Monitor subsequent DGTR findings and any Department of Revenue notification that may affect the applicable customs duty.
Official source: Directorate General of Trade Remedies (DGTR)
Investigation reference: DGTR SETU notifications. Locate the relevant PVC Suspension Resins investigation record and its preliminary findings.
06 | Export Promotion: RELIEF Initiative Extended
Component II extended until 31 March 2027
The Department of Commerce has extended the timelines under Component II of RELIEF (Resilience & Logistics Intervention for Export Facilitation), a time-bound intervention under the Export Promotion Mission, until 31 March 2027.
The extension was announced by the Ministry of Commerce and Industry on 26 October 2026 in view of continued geopolitical disruptions in West Asia and their impact on maritime logistics across the Gulf and adjoining regions.
Key points
- Extended timeline: Component II continues until 31 March 2027.
- Risk coverage: The initiative offers 95% risk coverage to encourage ECGC cover for eligible export shipments to specified regions.
- Policy timing: The stated benefit applies to eligible Standalone Policies and Whole Turnover Policies obtained on or after 16 March 2026.
- Eligibility conditions: Exporters must check the specified regions, applicable policy conditions and scheme requirements.
Exporters operating in affected trade corridors should review shipment exposure, ECGC cover and eligibility with their finance and logistics teams. The extension should not be treated as automatic coverage for every exporter, destination or shipment.
Official announcement: PIB: Department of Commerce extends RELIEF initiative until 31 March 2027
Related official source: DGFT
07 | Key Takeaways for Importers and Exporters
- MSME exporters: Review DGFT Trade Notice No. 32/2026-27 and the applicable conditions before applying for support under the relevant EPM intervention.
- Export refund matters: Review CBIC Circular No. 264/10/2026-GST if a historical claim or proceeding concerns the former Rule 96(10).
- Export realisation: Check Circular No. 263/09/2026-GST against outstanding receivables, permitted payment arrangements and any authorised dealer bank write-off.
- PVC Suspension Resins importers: Monitor the DGTR investigation and verify the product scope and subsequent official actions. Do not treat preliminary findings as a final duty notification.
- Exporters facing logistics risks: Review the RELIEF extension, ECGC cover and eligibility requirements before relying on scheme support.
- Compliance teams: Retain official documents and supporting records for internal review, audit and any subsequent representation to the authorities.
08 | Official Source Directory
- CBIC: Official website for customs notifications, circulars, instructions and GST circulars.
- DGFT: Official website for trade notices, notifications and foreign trade policy updates.
- DGTR: Official website for trade-remedy investigations and findings.
- DGTR SETU: Notifications and case updates.
- ICEGATE: Official customs e-filing portal.
- e-Gazette: Official Gazette of India for published statutory instruments.
- Press Information Bureau: Official government press releases.
09 | Verification Note & Disclaimer
This digest is prepared for informational and educational purposes. It is not a substitute for the full text of a notification, circular, trade notice, scheme guideline, investigation document or other applicable legal instrument.
Readers should verify the latest official document, effective date, amendments, eligibility conditions, product scope and applicable procedures before acting. Where a secondary source is provided for convenience, the official government publication should be treated as authoritative.
In trade-remedy matters, preliminary findings, final findings, recommendations and the actual imposition of customs duty are distinct stages. The applicable legal position must be determined from the relevant official records.
GST-related developments are included here only where they have a direct connection with export refunds, export realisation or international trade compliance. Judicial decisions of the Supreme Court, High Courts and CESTAT are covered separately through dedicated case-analysis articles and are not part of this Daily Digest.


Leave a Reply